When one paycheck supports everyone
The quotes are coming back in neat monthly numbers, but the decision doesn’t feel neat. The paycheck that covers the mortgage, groceries, and daycare also quietly covers the time it would take a partner to regroup if that income disappeared. It’s easy to tell yourself, “We have savings,” until you notice how quickly savings gets assigned to everything else—car repairs, a medical bill, a surprise school fee. The friction isn’t the math; it’s admitting which parts of the household are actually funded by one person’s continued ability to work.
In a single-income (or mostly single-income) household, life insurance stops being a “replace my salary” idea and becomes a continuity plan. If the surviving partner can’t immediately match the income, the shortfall shows up fast: housing payment timing, health insurance costs, and childcare logistics that suddenly need cash, not optimism.
I’ve found it helps to run two numbers side by side: a bare-minimum keep-the-lights-on figure (fixed bills + baseline living costs), and a “stabilization” figure that includes paid help (childcare, household services) for the months when capacity is lowest. The constraint is that the stabilization number is often what pushes premiums from comfortable to annoying.
That annoyance is useful data. If the premium only works at the bare-minimum number, it’s a signal to look for other levers later (term length, partial coverage layering), instead of pretending the household could instantly operate the same way on less.
Budget ceiling sets the first hard boundary
Once the “annoying” premium shows up, the next move is to stop debating ideals and set an actual ceiling. Not a theoretical “we can make it work,” but a number that still leaves retirement contributions, minimum debt payments, and a little slack for the month that goes sideways. If the quote only fits by pausing the 401(k) match or running the checking account to zero, that isn’t affordability; it’s borrowing from the future.
In practice, households tend to find the ceiling by backing into it: what can be auto-paid every month without watching the balance like a hawk? And because final pricing can shift with underwriting class, I treat the pre-underwriting premium as a range, not a promise.
That ceiling becomes the hard boundary. Coverage can expand later; a budget that breaks in month six usually doesn’t get repaired by good intentions.
Replace income or fund specific years?
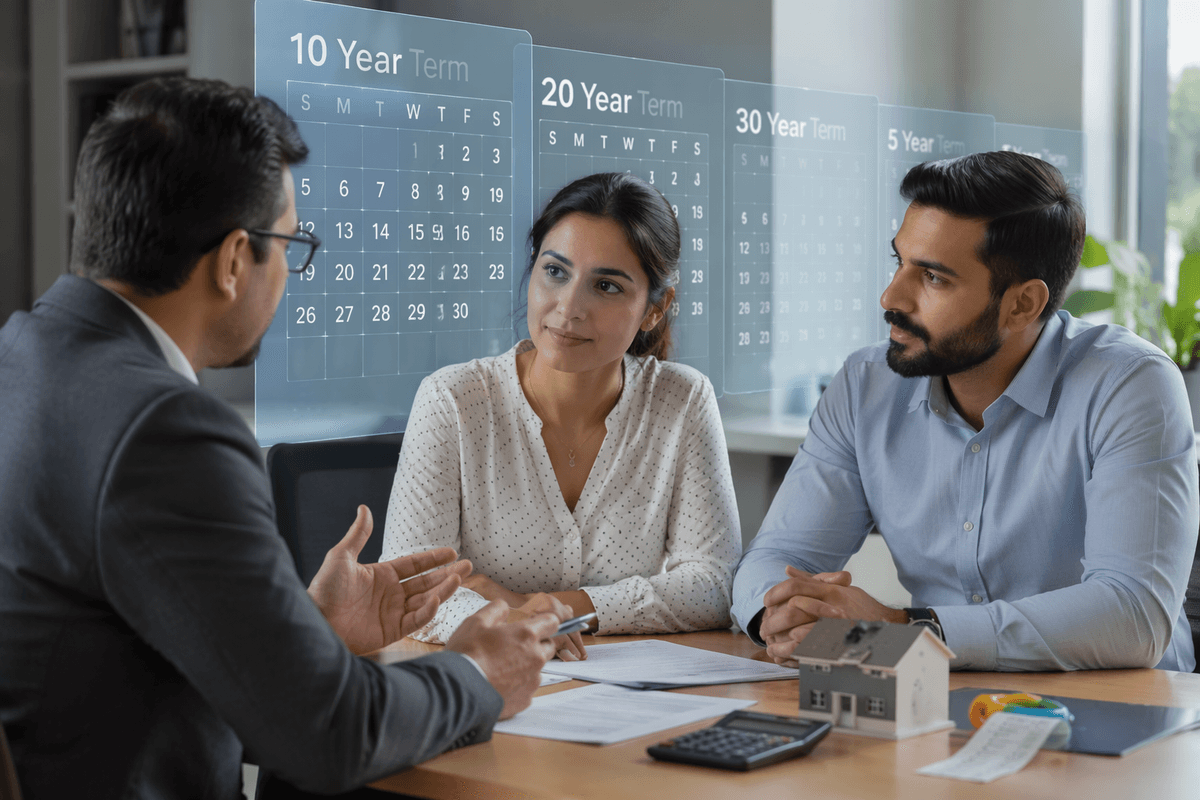
With the premium ceiling set, the next fork is subtle: buy a big “income replacement” number, or buy time. Income-multiple rules (10×, 12×) feel clean, but they ignore whether the surviving partner can return to work in 18 months or needs five years because childcare is the gating cost. The constraint is that the cleaner rule often prices you into a term you can’t comfortably keep.
I’ve had better results treating coverage as a stack of years to be funded: mortgage and other debt you’d actually retire, then a runway of household cash flow, then time-limited items like daycare. If you pick three, five, and seven years as checkpoints, you can translate them into a present-value lump sum using a conservative net return assumption and a realistic post-tax spending number.
That process usually yields a defensible range, not a single “right” figure—and it makes it obvious which years are expensive to insure versus expensive to live through.
Debt payoff feels obvious, but check trade-offs
Once the “fund specific years” math is on paper, debt tends to jump to the top because it’s concrete. “Just pay off the mortgage” feels like a clean answer, but it’s also the fastest way to inflate the face amount and blow past the premium ceiling. The constraint is timing: a 3% mortgage with a survivable payment schedule doesn’t create the same immediate failure risk as a variable-rate HELOC or a car loan that’s due every 30 days.
I separate debts into “must retire at death” and “can be serviced with the runway.” Must-retire is anything the surviving partner can’t realistically carry while re-entering work: high-rate revolving balances, short-term loans, and any debt tied to a co-signer or business guarantee. Serviceable debt is the fixed-rate mortgage if the payment fits inside the bare-minimum budget and there’s cash set aside for a few ugly months.
That sorting usually trims the number without pretending debt doesn’t matter—it just avoids buying insurance to eliminate the cheapest dollars on your balance sheet.
Childcare, college, and the costs that sneak in
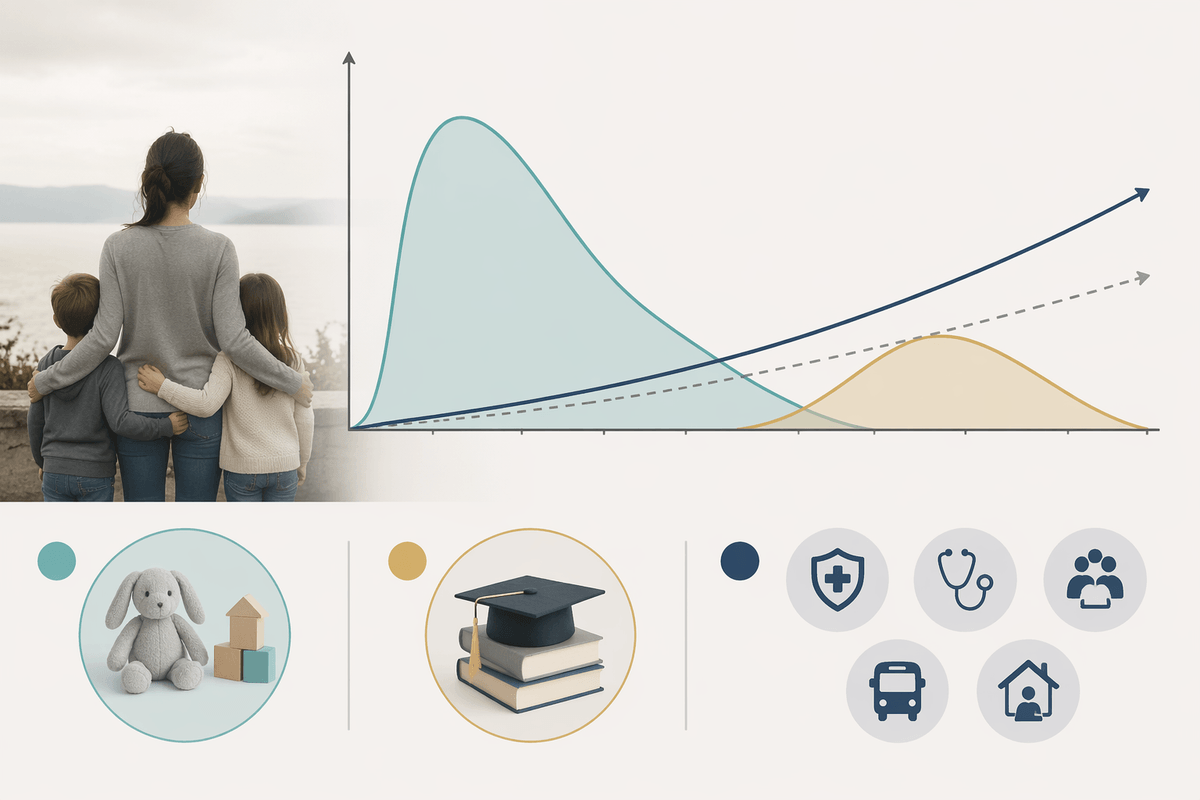
After debt gets sorted, the next line item that quietly wrecks the spreadsheet is paid care. Daycare isn’t just “a bill,” it’s the thing that determines whether the surviving partner can increase income at all. I’ve seen plans that assume a quick return to full-time work, then ignore that the cash crunch is worst in the exact years when childcare costs peak. The constraint is simple: if the policy amount doesn’t fund childcare, the income-replacement assumption is doing imaginary work.
College is the other trap, mostly because it feels optional right up until it doesn’t. Instead of adding a giant four-year number, I treat it like a separate choice: either fund a specific dollar amount per kid (modest, intentional), or explicitly leave it out and protect the basics first. Trying to “do everything” often forces a smaller term or a lower face amount—both of which can fail earlier than expected.
Then there are the sneaky costs: health insurance premiums shifting, higher out-of-pocket maxes, school-age summer coverage, transportation, even paid help during a rough year. These don’t look like debts, but they behave like required spending, and they’re usually what turns a tight quote into a fragile plan.
Term length workaround, then the expiry cliff
When the coverage number you actually want won’t fit under the monthly ceiling, the usual workaround is to shorten the term. A 10- or 15-year policy can make a “real” face amount suddenly affordable, which feels like solving the problem without touching retirement contributions. The constraint is that the savings are bought by moving the deadline closer, not by reducing the household’s exposure.
That deadline matters because the hard years don’t always line up neatly. If the younger child is three and the mortgage has 23 years left, a 15-year term is betting that income, childcare, and health all cooperate on schedule. People also layer terms (for example, 20 years plus a smaller 10) to keep premiums tolerable while protecting the messy early window.
The cliff shows up when the shorter term expires and the need hasn’t disappeared. Renewing at older ages can be punishing, and shopping again may collide with new medical history. The practical move is to treat the “cheap” term as a bridge and schedule a recalculation before it runs out, while you still have options.
Employer coverage and conversion surprises
Right after the “bridge term” idea starts to feel workable, employer life insurance tends to wander into the plan as a relief valve. The payroll deduction looks tiny, HR calls it “free” or “one times salary,” and it’s tempting to shrink the individual policy to make the monthly budget behave. The catch is that job-based coverage is tied to employment timing, not family timing, and mid-career households change jobs more often than they expect—sometimes right after a move, a layoff, or a health diagnosis.
I treat employer coverage as a bonus layer, not the base, because the fine print can be surprisingly constraining. Coverage caps may prevent you from buying enough, and increases can require evidence of insurability. Even when the amount is solid today, it may not follow you if you go part-time, switch employers, or step out for caregiving—exactly when paying for a new policy feels hardest.
The conversion option is the other gotcha. Yes, many plans let you convert to an individual policy, but the pricing is usually closer to permanent insurance than term, and the converted amount can be limited. If you’re counting on employer insurance to “be there,” it’s worth pricing the post-job scenario now, while the term quotes are still competitive and your underwriting risk is still a question mark—not a surprise.
Revisit after milestones so coverage stays right
The plan that feels “done” at purchase has a habit of drifting. Six months later there’s a refinance, a second kid, or a partner’s income changes—quietly moving the break-even point on the runway you thought you bought. The constraint is timing: the easiest moment to adjust is usually before a health change, but the moment you notice the mismatch is often after a big life event has already landed.
I like a simple trigger list, not an annual ritual: new mortgage or major rate reset, daycare ending (or starting), a job change that alters employer coverage, a meaningful raise, or a third child. Each trigger is a prompt to re-run the “must-retire debt + funded years” math, then check whether the premium still clears the ceiling without stealing retirement contributions.
If the need shrinks, it’s not always worth canceling—sometimes you reduce by dropping a small layer, or keep it to protect against the expiry cliff you already identified. If the need grows, the goal is adding coverage while you’re still insurable, even if that means a smaller add-on term rather than reopening the entire policy.