Intro: A stable job, a shaky housing forecast
The offer letter is solid, the bonus structure is finally predictable, and the bank’s pre-approval email makes the whole “buy now” idea feel strangely official. Then the rest of the world leaks back in. Listings sit longer than they used to, then a clean one disappears in two days. A friend swears prices are about to drop; another just “locked in” and acts relieved. Meanwhile rent keeps resetting higher at renewal, but it’s still a single number you can plan around.
What makes this moment tricky isn’t qualifying. It’s choosing a timeline while the forecast refuses to hold still. The decision stops being about whether owning is “better” and turns into whether the next 12–36 months needs flexibility, or a fixed address—and what it costs to be wrong either way.
When mobility matters more than building equity
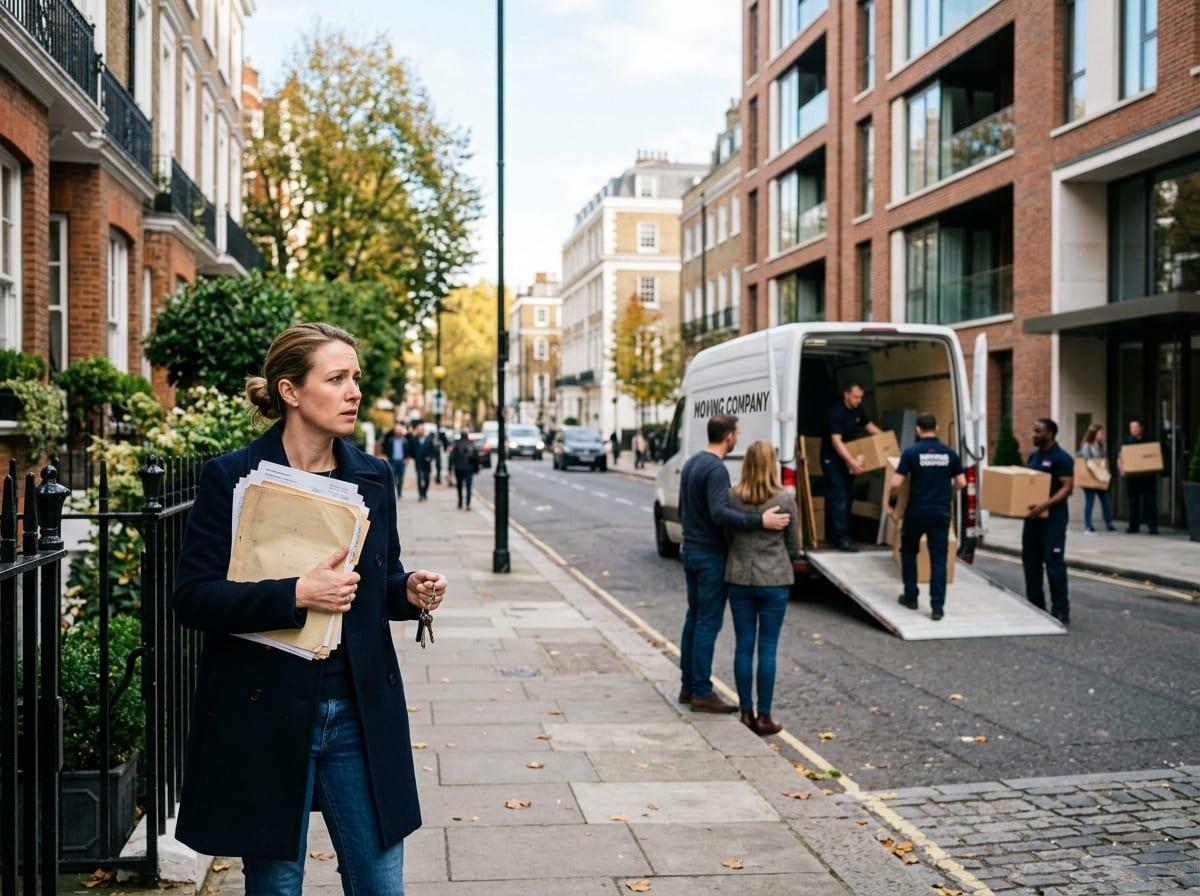
The question shifts fast once the job feels “stable” but the role still has a two-year reshape risk: promotion, reorg, better offer, partner’s move. Equity sounds like progress until the timeline shortens and the exit costs get loud. In expensive metros, selling inside a few years can mean commissions, transfer taxes, staging, and a market that may not cooperate on the week you need it to.
Mobility has a price, but renting prices it upfront. A lease break fee and a moving truck are annoying; they’re also capped and knowable. Ownership turns the move into a financing event: can the home rent for enough to cover PITI, HOA, and repairs, or does it become a monthly subsidy while you’re trying to start over elsewhere?
If the horizon is genuinely 12–36 months, flexibility is no longer a lifestyle preference—it’s a risk control.
Cash flow pressure tests the monthly payment story
After the mobility math, the next pressure point is the month-to-month reality. A loan officer can make the payment look “close to rent,” especially if you focus on principal and interest and treat everything else as background noise. But the budget doesn’t. Property taxes step up after reassessment, insurance is rarely flat, HOA dues drift, and utilities often rise the moment the square footage does. Even before repairs, the “single number” turns into a stack of withdrawals with different timing.
That stack matters because high earners still run into cash-flow friction: bonus-based income, uneven RSU vesting, childcare, student loans, travel. A mortgage is a fixed obligation, but the rest of life isn’t. If the payment only works when the bonus hits, it’s not really affordable; it’s leveraged on timing.
And once cash gets tight, the comparison flips. Rent hikes are painful, but they don’t trigger escrow shortages, late fees, or a forced decision to carry a balance—right when rates on everything else might be higher too.
Volatility: prices, rates, and the risk of timing
When the budget is already tight, volatility stops being abstract and starts showing up as deadlines. Rate quotes move between the open house and the offer review, and the “affordable” payment you modeled last week can quietly turn into a different loan today. Paying points or extending a lock buys time, but it’s still money out the door, and it doesn’t protect the home’s price.
Prices swing in a different rhythm. If comps soften mid-escrow, an appraisal gap can force a choice: bring extra cash, renegotiate, or walk and eat inspection and lock costs. If prices jump, the down payment target rises and the search resets. Either way, timing risk is a liquidity test, not a philosophical debate.
The uncomfortable part is that refinancing isn’t a plan; it’s a hope. Treat rates and prices as scenarios, then decide whether you can live with the downside path.
Maintenance realism versus the convenience premium
The first time ownership feels different isn’t the closing table—it’s the first broken thing. A $1,200 repair on a random Tuesday isn’t catastrophic for many high earners, but it’s disruptive in a way rent rarely is. The cost is only half the issue; the timing, the vendor roulette, and the fact that “cheap now” can turn into “replace the whole system” are what chew up attention.
In a condo, the convenience premium is mostly outsourced maintenance, but it shows up as HOA dues and special assessments that don’t respect your cash-flow calendar. In a single-family home, the dues disappear and the surprises move inside the walls. Either way, the all-in comparison has to include a repairs line item that’s real enough to hurt and boring enough to fund every month.
If the plan is to stay flexible, the question becomes whether you want to spend the next 12–36 months buying stability—or managing a small property operation on top of your actual job.
Reasonable choice, worse outcome: the starter home trap
The most tempting compromise is the “starter” purchase: smaller, a little dated, something that feels safe because it isn’t the dream house. On paper it can look like a disciplined move—lower price, easier approval, a chance to stop rent hikes. The trap is that expensive metros don’t always price “starter” as cheap; they price it as scarce. So the payment still stretches, and the exit still carries full transaction costs.
Then the timeline shifts. A good job change shows up, or a partner’s commute stops working, and selling quickly turns the reasonable choice into a math problem. If prices are flat, the equity you expected can get eaten by commissions, transfer taxes, and the repairs you deferred because the place was “temporary.” If prices dip, the starter home can be the first thing you’re reluctant to list—right when flexibility was the point.
That’s how a prudent purchase becomes a worse outcome: not because buying was irrational, but because the middle option concentrates the same risks with less staying power.
Opportunity cost: the down payment’s alternate life
The down payment is usually treated like the ticket into homeownership, but it also has a quieter job: keeping options open. Once it’s converted into equity, accessing it means a refinance, a HELOC you may not qualify for when you need it, or selling on the market’s schedule. In a 1–3 year window, that illiquidity can matter more than the theoretical return, especially if the same period includes job volatility, a move, or a stretch of higher everyday costs.
What gives the rent-versus-buy comparison teeth is asking what that cash would do instead. Sitting in T-bills or a high-yield savings account won’t make a great story, but it can cover an unexpected gap without forcing a housing decision. Investing it may outperform, or it may drop right when you’re trying to relocate. Either way, the opportunity cost isn’t just “missed gains”—it’s whether the down payment is allowed to function as a buffer while the timeline is still unsettled.
A workable rule set for “some people”
After all that modeling, what usually helps is a small set of rules that doesn’t pretend to forecast prices. Start with horizon: if there’s a real chance you leave before year 4–5, treat buying as a lifestyle choice and assume you may not break even after commissions and transfer taxes.
Next, run a cash buffer test. If you can’t hold 6–12 months of total housing cost (PITI + HOA + insurance) plus a repairs reserve without leaning on a bonus cycle, the “close to rent” story is too fragile.
Finally, price the downside: flat prices, no refi, one special assessment. If that version still feels workable, buying is “some people” reasonable—even if it’s not guaranteed optimal.