Your CD matures, and rates feel uncertain
The maturity date lands on the calendar and suddenly the “set it and forget it” feeling is gone. The bank’s renewal notice shows a new APY that may be higher than your last term, or oddly lower, and the fine print quietly shortens the window to decide—often a week or so—before the CD auto-rolls. Meanwhile, the rate headlines keep changing, and it’s hard to tell whether locking again is being disciplined or just being late.
What makes this moment tricky is that doing nothing is still a choice with real costs. Re-upping can mean another stretch of limited access, while moving the cash out can mean earning less immediately or taking on a new kind of uncertainty. This is the point where “safe” stops being a feeling and turns into a set of trade-offs you have to price.
What you actually wanted your CD to do
In practice, the CD probably wasn’t about “beating the market.” It was about making a slice of cash behave: earn more than idle checking, avoid surprise drops, and stay out of reach of impulsive spending. The trade was acceptable because the rules were simple—fixed rate, fixed end date—and the worst-case outcome felt bounded as long as you could avoid an early withdrawal penalty.
That intention matters now because it sets your real benchmarks. If the money is tied to a near-term expense, the CD was functioning like a scheduled invoice—liquidity on a date, not “growth.” If it was meant as a calm buffer, you were really buying stability plus a little yield, with minimal monitoring. The frustration at renewal is often a signal that the goal wasn’t “highest APY,” it was predictable progress without needing perfect timing.
The mismatch: steady interest, but real purchasing power
The awkward part is that the CD can do exactly what it promised and still leave you worse off in real terms. The statement balance rises in a straight line, month after month, and that smoothness feels like progress. But if everyday costs rise faster than your interest, the CD is quietly shrinking in purchasing power while looking “up” on paper. That gap is easy to miss because the CD’s rate is explicit, while inflation shows up as a series of small price changes that don’t arrive as a single line item.
Even when the CD rate is competitive versus a savings account, the lockup changes the math. You’re committing to a fixed nominal return while the real-world baseline keeps moving, and you can’t adjust midstream without a penalty or a reset. If inflation cools, the CD can look brilliant. If inflation re-accelerates, the same CD becomes a slow leak—especially for money you expected to keep “safe” for a year or two, not for decades. The mismatch isn’t that CDs are bad; it’s that “no price swings” doesn’t automatically mean “no erosion.”
First pivot: options that keep money boring
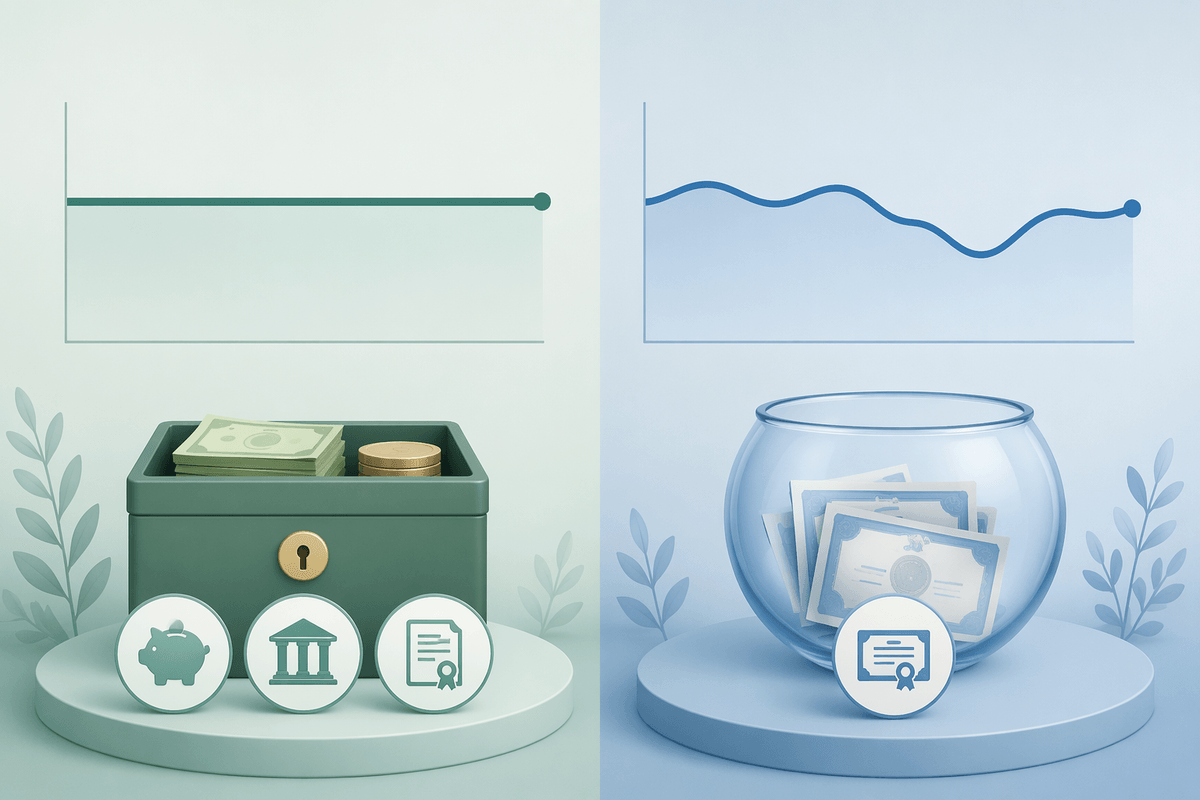
So the first move usually isn’t to get adventurous—it’s to keep the money boring, just with fewer handcuffs. If the renewal APY looks fine but you hate the feeling of being trapped, the closest substitute is often a high-yield savings account or a money market deposit account at a bank you trust. The friction is that the rate can change whenever the bank feels like it, so you’re swapping “locked” for “floating,” but you get daily liquidity and you stop paying an early-withdrawal penalty in your head.
If you’re willing to step outside the bank, money market funds and Treasury bills are the next “still boring” tier. T-bills, in particular, replace the CD’s fixed end date with a new kind of certainty: the U.S. Treasury maturity date and a known yield if held to maturity. The constraint shifts to mechanics—opening a brokerage account, placing orders, and choosing a ladder (for example, 4-, 8-, and 13-week bills) so cash is predictably coming due instead of all at once.
For cash that can sit a bit longer, short-term bond funds can look tempting, but they’re where “boring” starts to wobble because the price can dip when rates move. If the goal is to preserve that CD-like steadiness, the cleaner comparison is: stable value plus easy access (HYSA/MMF/T-bills) versus a slightly higher expected yield that may come with a statement balance that doesn’t move in a straight line.
Second pivot: accepting small price moves on purpose
The next step tends to happen after you’ve tried the “still boring” options and noticed the ceiling: liquidity is great, but the yield can flatten quickly, and every reset becomes another small timing decision. At that point, a measured amount of price movement starts to look less like danger and more like a tool—if the money doesn’t need to be perfectly flat week to week. The constraint is psychological as much as financial: you have to be willing to see a statement dip a bit without treating it as a mistake.
This is where short-duration bond ETFs and high-quality corporate/agency funds earn a place, not as a reach for return, but as a controlled trade: a little interest-rate risk in exchange for a higher expected yield than cash. The key is matching duration to your patience. A fund with a 1–2 year duration can still move down if rates jump, but the income stream is designed to rebuild returns over time. If you might need the money in three months, it’s the wrong tool; if you can give it a year or two, small swings stop being random noise and start being the cost of not being fully locked into today’s cash rate.
The surprise factor: taxes quietly change returns
After you’ve done the work of comparing yields and tolerating a bit of price movement, the return can still get quietly shaved down by where the interest shows up on your tax return. A CD’s interest is ordinary income, and most cash-like alternatives are the same—so the “best” APY can end up being the one that simply threw off more taxable income in the same year you were already in a higher bracket. The constraint is timing: a maturity in December versus January can change which tax year takes the hit.
This is also where Treasuries have an edge that doesn’t show up on a bank’s renewal notice. Treasury bill interest is generally exempt from state and local income tax, while bank CD interest and most money market fund yields usually aren’t. Meanwhile, bond funds can mix income with small capital gains or losses, which may help or hurt depending on the year. It’s not dramatic, but it’s enough to turn two “similar” yields into different after-tax outcomes.
A rollover plan you can repeat each maturity
By the time the next maturity arrives, the goal is that you’re not reinventing the decision under a one-week auto-roll window. A repeatable plan looks more like a schedule than a forecast: keep a defined “flat” sleeve (T-bills or a government money market fund) for near-term needs, and a defined “small-moves” sleeve (short-duration bond fund) only for money you can leave alone for a year or two. The constraint is calendar-based—set maturities so something comes due monthly or quarterly, not all at once.
At each maturity, roll only the piece you still don’t need, and only into the same two buckets unless your timeline changed. If rates jump, new rungs catch up; if rates fall, older rungs carry you. The review step is boring on purpose: check after-tax yield, confirm liquidity needs, then place the next rung and move on.