When a big conversion feels like a now-or-never move
The pressure usually shows up right after a job change, a sabbatical, or the first year of retirement—income dips, and the Traditional IRA/401(k) balance is still large. The spreadsheet makes it look clean: convert a big chunk “while the bracket is low,” pay the bill, and move on. Then the frictions surface. The withholding has to come from somewhere, the state tax might be different next year, and one oversized conversion can quietly push Medicare premiums higher later or erase a credit you assumed you’d keep.
So the decision starts to feel like a deadline even when it isn’t. The useful shift is to treat the year as a pricing window, not a one-time door: what matters is the all-in marginal rate on the next converted dollar, and how quickly that price jumps as income stacks up.
Start with the rate you’re actually buying
The first number to write down isn’t the bracket headline—it’s the marginal rate on the next dollar of ordinary income in this specific year. A Roth conversion stacks on top of wages, interest, cap gains, and any one-time items, so the “price” can change mid-conversion. If you’re paying from taxable cash, the bill is due within months, not in some abstract lifetime model.
Then adjust for the add-ons that don’t show up as a separate tax line. More conversion income can make additional Social Security taxable, chip away at ACA subsidies, trigger the NIIT, or push Medicare MAGI into a future IRMAA tier. Those effects behave like surtaxes because they raise the tax owed per extra dollar converted.
Once those are in the same calculation, the bracket becomes a label, not the decision.
Why the 12% bracket often feels like a safe bet
In that pricing-window mindset, the 12% bracket is where many plans settle down. It’s often the last place where the “headline” rate and the “all-in” rate stay reasonably close, because you’re frequently still below the income ranges where phaseouts and benefit interactions start stacking quickly. The tax bill is still real money, but it tends to be a bill you can fund from cash without selling appreciated assets or triggering a cascade of extra taxes.
It also feels psychologically clean: converting up to the top of 12% creates a visible ceiling, and it’s hard to regret paying 12% on dollars that might otherwise be taxed later at 22%+ after RMDs begin. The catch is that “safe” depends on what else is in the year—especially ACA credits, early Social Security, or state tax—because those can turn a 12% bracket into something closer to a mid-teens marginal price.
The 22% bracket: common target, common regret
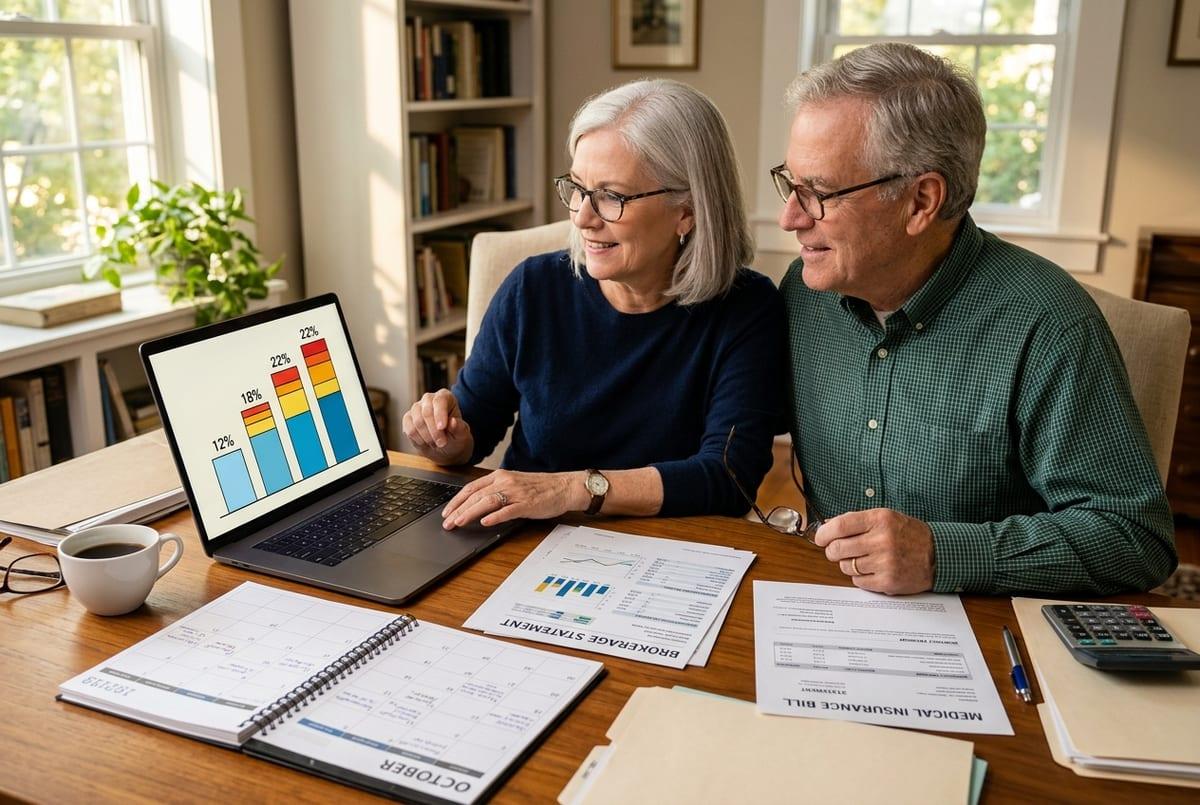
After a year or two of converting to the top of 12%, the next dollars often look “obvious.” The jump is still just a bracket, the math still fits on one screen, and 22% starts to feel like the realistic hedge against future RMDs. The friction usually appears when that extra conversion forces a funding decision: more cash than expected, a taxable sale at the wrong time, or estimated payments that land uncomfortably close to a penalty line.
The regret tends to come from treating 22% as a single price. In practice, those dollars are often the ones most likely to stack with side effects: more Social Security pulled into taxation, a higher NIIT exposure, or a Medicare MAGI step that raises premiums two years later. By the time the full “all-in” marginal rate is tallied, the 22% target can quietly behave like something meaningfully higher.
What changes outcomes is not avoiding 22% altogether, but noticing when the first slice is clean and when the later slice is buying hidden cliffs along with the conversion.
Hidden cliffs that make a bracket look worse
Those “later slice” dollars are where the bracket label stops being helpful, because the next $1,000 of conversion can change more than the income tax line. The most common surprise is Medicare: an extra bit of MAGI this year can push you over an IRMAA tier and raise Part B/Part D premiums two years later, turning a clean 22% purchase into something that behaves like a one-time surcharge.
Social Security has a similar feel once benefits start. A conversion can make more of the benefit taxable, so the effective marginal rate in that band is higher than the headline bracket, even though nothing “new” appears on the return. For early retirees on ACA coverage, the cliff can be immediate: a slightly larger conversion can shrink credits sharply, so the all-in price spikes right where you expected smooth bracket math.
Then there are quieter phaseouts—credits, deductions, and the NIIT boundary—that don’t hurt until you graze them. The practical constraint is timing: you often don’t see the real cost until you reconcile the return or get the Medicare notice, which is why that last chunk of a bracket is the one worth stress-testing.
Filling the 24% bracket can be rational sometimes
After getting burned by a 22% “later slice,” the instinct is to swear off higher brackets altogether. But some households run into a different constraint: the pre-tax balance is so large that leaving it alone just concentrates taxes later—bigger RMDs, a surviving spouse filing single, and less room to manage income around Medicare tiers.
That’s where 24% can be a deliberate choice, not a default. If the conversion dollars are “clean” (no ACA credits in play, Social Security not yet started, NIIT not being crossed, and no IRMAA tier being clipped), paying 24% now can be cheaper than a future mix of 28%+ effective rates created by stacked RMDs and benefit interactions.
The review test is funding and stability: you can pay the tax from cash without a forced taxable sale, and you can repeat the move for a few years. If it’s a one-off spike that also buys a Medicare surcharge, it stops looking like a 24% purchase.
Timing choices: one-year spike or multi-year plan
The temptation is to “solve” the IRA in a single low-income year, especially before Social Security or RMDs start. The one-year spike can work when the tax is fundable from cash and the spillovers are contained—no ACA credits to protect, no IRMAA tier being clipped, and no big capital gains forcing the next dollar into a different price band. The risk is that the last dollars converted are the most expensive, and you only discover that after the year closes.
A multi-year plan trades speed for control. Keeping conversions smaller can let you stop just below a Medicare or credit threshold, then reassess after dividends, Roth growth, and market returns shift the base. The constraint is patience: if future income rises sooner than expected, the “window” closes and you’re left converting later at a higher all-in rate.
In practice, the cleaner choice is often a hybrid: take the obvious cheap slice this year, then spread the messy slice across years where you can aim between cliffs instead of jumping over them.
A practical way to pick your conversion ceiling
By the time the plan reaches a “hybrid,” the ceiling stops being a bracket and turns into a number you can defend under messy inputs. Build a simple conversion ladder in a spreadsheet: start with current taxable income, then add conversion dollars in steps (say $5,000 or $10,000) and compute the extra federal tax each step creates. Then layer in the items that behave like taxes—lost ACA credits, extra Social Security pulled into taxation, NIIT exposure, and any IRMAA tier you’d land in based on this year’s MAGI.
What you’re watching for is the first sharp jump in the all-in marginal rate. Set the ceiling just below that jump, not at the top of a bracket, unless the next band is still “clean” and you can repeat it for multiple years. If the jump is close, treat it like a price quote that expires on December 31 and revisit after dividends, gains, and withholding are final.