When the offer is accepted, risk starts
The moment the seller signs, the tone of the purchase changes. Up to that point, the offer mostly feels like positioning—price, credits, maybe a few favors on timing. Once it’s accepted, the same terms turn into a calendar with consequences. Lenders still haven’t cleared the file, inspectors haven’t opened a panel, and the title company hasn’t ruled out messy surprises, but the contract clock is already running.
What usually catches first-time buyers is how quickly “normal” life events collide with deadlines: a lender asks for one more document, an inspector can’t get in until next week, a holiday slows down signatures. If you miss a notice date by even a day, you may lose a right you assumed you had, or you end up paying to extend the deal.
So the acceptance day is less a celebration than a handoff. You’re now managing risk through timelines—who has to deliver what, by when—and every delay needs a written fix, not a verbal promise.
The purchase contract decides your real leverage
The next few days tend to feel negotiable—until the contract language proves otherwise. Most buyers assume leverage comes from being “the winning offer.” In practice, it comes from what the agreement lets you do if something goes sideways, and how fast you have to act. A three-day inspection window versus ten days isn’t just pacing; it changes whether you can get a second opinion, collect bids, and still send a clean notice on time.
Pay attention to what counts as written notice, where it must be delivered, and whether silence is treated as acceptance. Some forms auto-remove contingencies unless you cancel in writing by a deadline. Others require the seller to respond before anything changes. That difference decides who’s pressured when the inspection report lands, not the headline price.
Before signing, ask your agent or attorney to point to the exact clause that (1) lets you terminate, (2) forces you to negotiate, or (3) makes you proceed. If they can’t do it quickly, you’re likely agreeing to more certainty than your timeline can support.
Earnest money: refundable until it isn’t
That pressure shows up fast in the earnest money deposit. It feels like a good-faith placeholder, but once it’s in escrow it becomes the simplest remedy for the seller if you’re in default. The contract usually treats it as liquidated damages up to a stated cap, which is why the “small” number can still sting.
In most financed purchases, the deposit is functionally refundable only while a valid contingency is still open and you deliver the right cancellation notice on time. Miss the financing or inspection notice date, waive something in writing, or let an auto-removal clause trigger, and the same deposit starts looking nonrefundable—without any dramatic warning.
Even when you’re entitled to it, getting it back can be slow. Escrow often won’t release funds until both sides sign, and a seller who’s upset about timing or repairs can delay that signature. Ask, before you deposit, what document releases funds, how disputes are handled, and what deadlines keep your refund clean.
Contingencies that save you, then box you in
By now the deposit is sitting in escrow and the calendar is tight, so contingencies are the only clean exits left. They read like protection—inspection, appraisal, financing, sale of another home—but each one is also a timer that ends in either a written removal or a written cancellation. If the form treats silence as removal, the “safety net” can vanish while you’re still waiting on a report or a lender condition.
The trap is how quickly a contingency turns into leverage for the other side. Once you request repairs or a credit, you’re no longer just investigating—you’re negotiating. Many contracts let the seller refuse and keep the deal alive, forcing you to either proceed as-is or cancel within the contingency window. If you wait for contractor bids and the deadline passes, you can end up stuck closing or paying for an extension.
The practical move is to map each contingency to the exact notice method and cutoff date, then ask what happens if the seller doesn’t respond. That answer determines whether you’re protected, or simply boxed in on schedule.
Disclosures and due diligence hide in plain sight
After the contingency windows are on your calendar, the paperwork flood starts. Disclosures arrive as a stack of PDFs that look routine, and the pressure is to “just sign so we can stay on schedule.” That’s when buyers miss the part that matters: many disclosure packages aren’t something you negotiate in the abstract; they’re evidence you either reacted to on time or accepted by moving forward.
Read them like they’re a set of test questions. Prior insurance claims, water intrusion notes, permit gaps, “as-is” language, neighborhood nuisances, or a line about unpermitted work can change what your lender will tolerate and what you’ll be stuck repairing. If something is unclear, treat it as a deadline item: ask for documents, invoices, permits, and receipts, and get the answers in writing while your inspection and cancellation rights still exist.
Due diligence is less about discovering every defect and more about creating a clean record that you asked the right questions before you lost the ability to walk.
Title search and insurance: the quiet dealbreaker
Once disclosures are back in your inbox, the next “quiet” file is the title package. It rarely feels urgent until the title commitment shows an exception you can’t live with, and suddenly the closing date becomes a moving target with rate-lock days burning.
The title search is basically a risk inventory: old deeds of trust that were never released, tax liens, judgments, boundary issues, easements that limit use, or a recorded tenant/HOA right that wasn’t obvious from the listing. Any one of these can stop a lender from funding, or force a last-minute renegotiation when the seller needs time (and money) to cure it.
Title insurance doesn’t “fix” problems; it covers what the policy covers, and the exceptions matter. Ask what items are excluded, what endorsements your lender requires, and the deadline to object—because clearing title often takes longer than your contract allows.
HOA and condo documents can change the deal
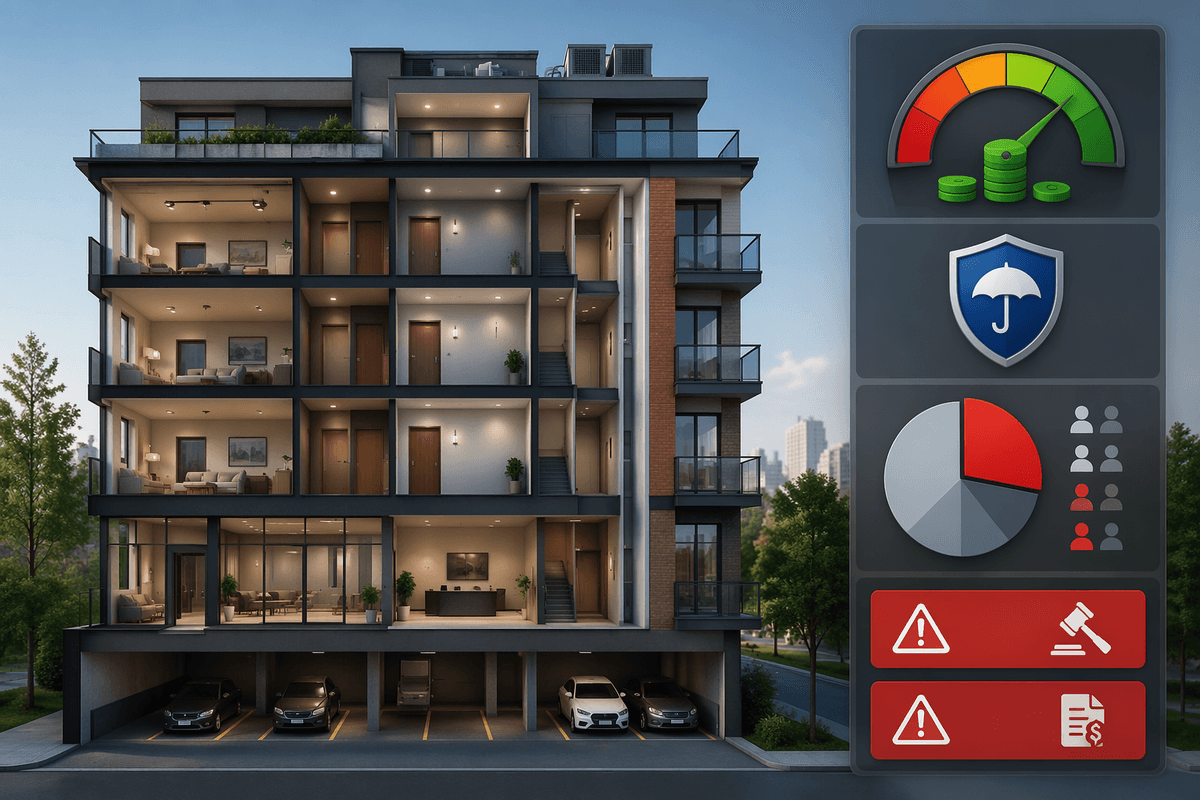
By the time title looks mostly clean, the HOA packet can be the thing that reopens the whole risk picture. It often arrives late, costs money to order, and comes with a short review window. Buyers treat it like housekeeping paperwork, then realize the rules and the budget can directly affect use, resale, and even whether the lender will close.
The friction is rarely one dramatic clause. It’s small constraints piling up: rental caps that block future flexibility, pet limits, parking assignments that don’t match what was promised, move-in fees, or pending special assessments that function like a hidden price increase. Meeting minutes can signal ongoing water intrusion, elevator repairs, or litigation—issues that can raise dues, trigger new assessments, or scare off financing.
Before you sign off, ask for the current budget, reserve study, insurance summary, delinquency rate, and any notice of pending assessments or lawsuits. If anything is missing or “still coming,” treat that as a timing problem with real leverage: extend your review period in writing, or keep an exit open while the documents catch up.
Closing week: documents, fees, and last-minute surprises
Closing week rarely feels like a finish line. It feels like everyone suddenly needs a signature “today,” while the lender is still clearing conditions and the title company is finalizing figures. If your rate lock expires in five days and the seller won’t move the closing date, small delays—an updated pay stub, a last bank statement page, a missing HOA invoice—start carrying real dollar consequences.
Expect a closing disclosure that’s close, then different. Recording fees, prepaid interest, escrow reserves, transfer taxes, and lender charges can shift, and seller credits don’t always land where buyers assume. If the cash-to-close jumps, the fix is usually time you don’t have, not negotiation power.
Then comes the surprise that feels “minor” until it isn’t: a final walk-through issue, a required repair receipt, a lien payoff number that changed, or an underwriter asking for one more document. The practical move is simple: ask who can delay funding, what your hard stop date is, and what happens to your deposit and rate lock if closing slides.